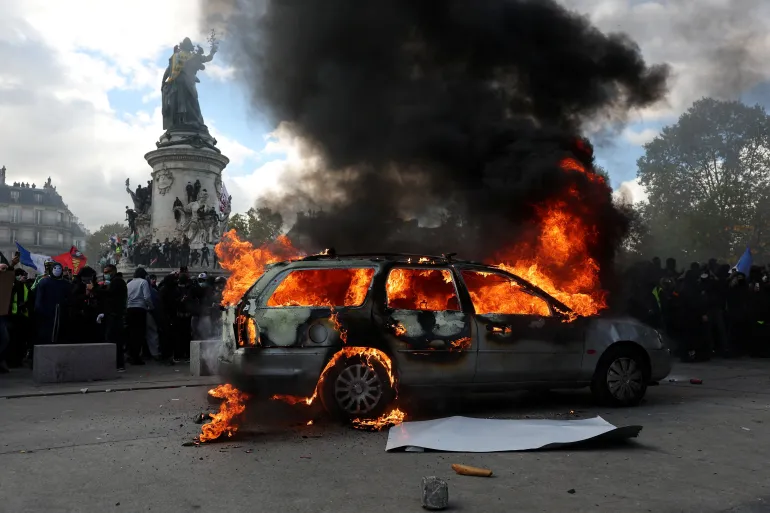
France is facing growing economic pressure as rising public debt, slow economic growth and increasing living costs fuel public dissatisfaction. The crisis has also intensified protests across the country, with demonstrators demanding better public services, improved living conditions and stronger government support.
One of the major concerns is the country’s high unemployment rate, particularly among young people. While overall unemployment stands at around 8%, youth unemployment is close to 20%. Economic growth has also weakened, with forecasts suggesting growth of just 0.4% in 2026 and 0.7% in 2027, according to the International Monetary Fund’s projections cited in recent reporting.
The government is also struggling with rising debt and a widening budget deficit. France’s public debt has crossed 118% of its GDP, while its fiscal deficit is projected at 5.4% of GDP in 2026. At the same time, the government spends heavily on pensions, healthcare and other welfare programmes. An ageing population is adding further pressure, as fewer working-age people may have to support a growing number of retirees.
Higher borrowing costs are making the situation more difficult. Investors are demanding higher returns to lend money to the French government, increasing the cost of servicing existing debt and leaving less room for other public spending.
France now faces the challenge of strengthening economic growth while controlling government expenditure. Possible measures include improving productivity, increasing employment and reforming pension spending. However, attempts to reduce welfare costs or raise the retirement age have faced strong public opposition, making economic reforms politically challenging.